| FINANCIAL
COMMENTARY (continued) |
| |
|
| Earnings continue
to grow strongly |
| |
| Debt capital
– US$73 million |
Capital has traditionally been a scarce resource
for Brait and consequently the group has always preserved and
managed its capital judiciously. At the same time, Brait has
had to balance this resource within the limits of its dividend
policy which has been to distribute regular and substantial
dividends as part of Brait's goal of generating incremental
long-term wealth accumulation for shareowners.
Brait currently has a US$13,0 million (ZAR80 million) unsecured
shortterm banking facility which it has utilised to meet its
working capital and short-term operational financing needs.
This facility though, has not been substantial enough for Brait
to pursue its longer term growth strategy. Brait has been reluctant
to raise new equity capital to fund its growth due to the perceived
market underpricing of Brait's equity.
Over the last twelve months the accessibility to unsecured funding
as well as the cost of raising corporate debt finance has declined
significantly in South Africa. Importantly for Brait, this has
presented a window of opportunity to raise a significant amount
of low cost, longterm debt which will meet the group's need
for capital to expand its operations.
Immediately prior to 31 March 2006, Brait secured a long-term
debt facility and has drawn down the full capital balance. The
principal terms of the facility are as follows: |
| • |
Amount: |
ZAR450 million (approximately US$73 million) |
| • |
Instrument: |
Redeemable preference shares issued by Brait South Africa
Limited |
| • |
Rate: |
78% of the South African prime rate on a floating rate
basis |
| • |
Term: |
Seven year loan with a redemption schedule commencing
annually at the end of the fourth year |
| • |
Currency: |
ZAR |
| • |
Guarantees: |
Brait S.A. group underpin |
| • |
Early redemption: |
Brait is entitled to an early redemption at any time
prior to the specified settlement dates. |
|
| |
| Brait intends to apply the capital as follows: |
| • |
to accelerate growth of existing operations; |
| |
– |
increase Brait IV co-investment |
| |
– |
new private equity proprietary investing |
| |
– |
additional seed capital and product development in Specialised
Funds |
| |
– |
loan book growth and expansion in Bayport |
| • |
to initiate new organic business activities;
and |
| • |
to facilitate BEE investing opportunities. |
|
| |
| Brait may also consider a limited share buyback
programme. |
| |
| The outcome of the deployment of the additional
capital should: |
| • |
enhance earnings growth from investment returns; |
| • |
increase the growth in funds under management; |
| • |
improve Brait's earnings yield from capital and share
buyback efficiencies; and |
| • |
improve Brait's market rating by decreasing earnings
dependency on private equity investing income. |
|
| |
| Brait will continue to follow its stringent investment
disciplines before investing this new capital. Subsequent to
year-end, Brait has deposited a large portion of the capital
drawn with the Brait Absolute Fund as a cautionary interim investment
until such time as it is allocated to the group's operations. |
| |
| Page
up |
| |
| Operations
and performance |
Brait has continued its strong performance in
the previous year with improved earnings in all business areas.
This performance was primarily driven by the private equity
and group investment operations.
Key financial scorecard performance deliverables this year have
been: |
| • |
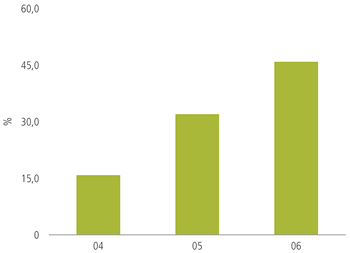
an annual 45,9% return on shareowners' funds and a cumulative
long-term ROE since 1 April 2003 of 36% – this substantially
exceeds the group's long-term target ROE of 20% in US
dollars; |
| • |
cumulative fund commitments of US$1 529
million exceed the group objective of US$852 million by
79%; and |
| • |
cumulative funds invested increased by 72% from US$615
million to US$1 060 million against the group objective
of 20% per annum. |
|
| |
| |
| Return on
equity (ROE) |
 |
| |
| Page
up |
| |